

Conventional
- Down payment
- As low as 3% for eligible programs
- Mortgage insurance / fees
- Private mortgage insurance may apply below 20% down
- Key considerations
- Credit, income and property requirements vary
Florida’s Top-Rated Direct Lender4.8 Google RatingA+ BBB Rating
1st Florida Lending | Mortgage Loan Programs
Low Down Payment Options. Down Payment Help. One Clear Path Home.
STOP RENTING AND START OWNING. FOLLOW 10 SIMPLE STEPS FROM SAVING TO GETTING THE KEYS TO YOUR FIRST HOME.
Buying your first home is easier when you know what comes next. As a direct lender with in-house underwriting, 1st Florida Lending helps first-time buyers compare conventional loans from 3% down, FHA from 3.5% down, zero-down VA and USDA options for eligible borrowers, and Florida down payment assistance. Learn at your own pace, then talk with a licensed loan officer who compares your choices instead of pushing one loan on everyone.
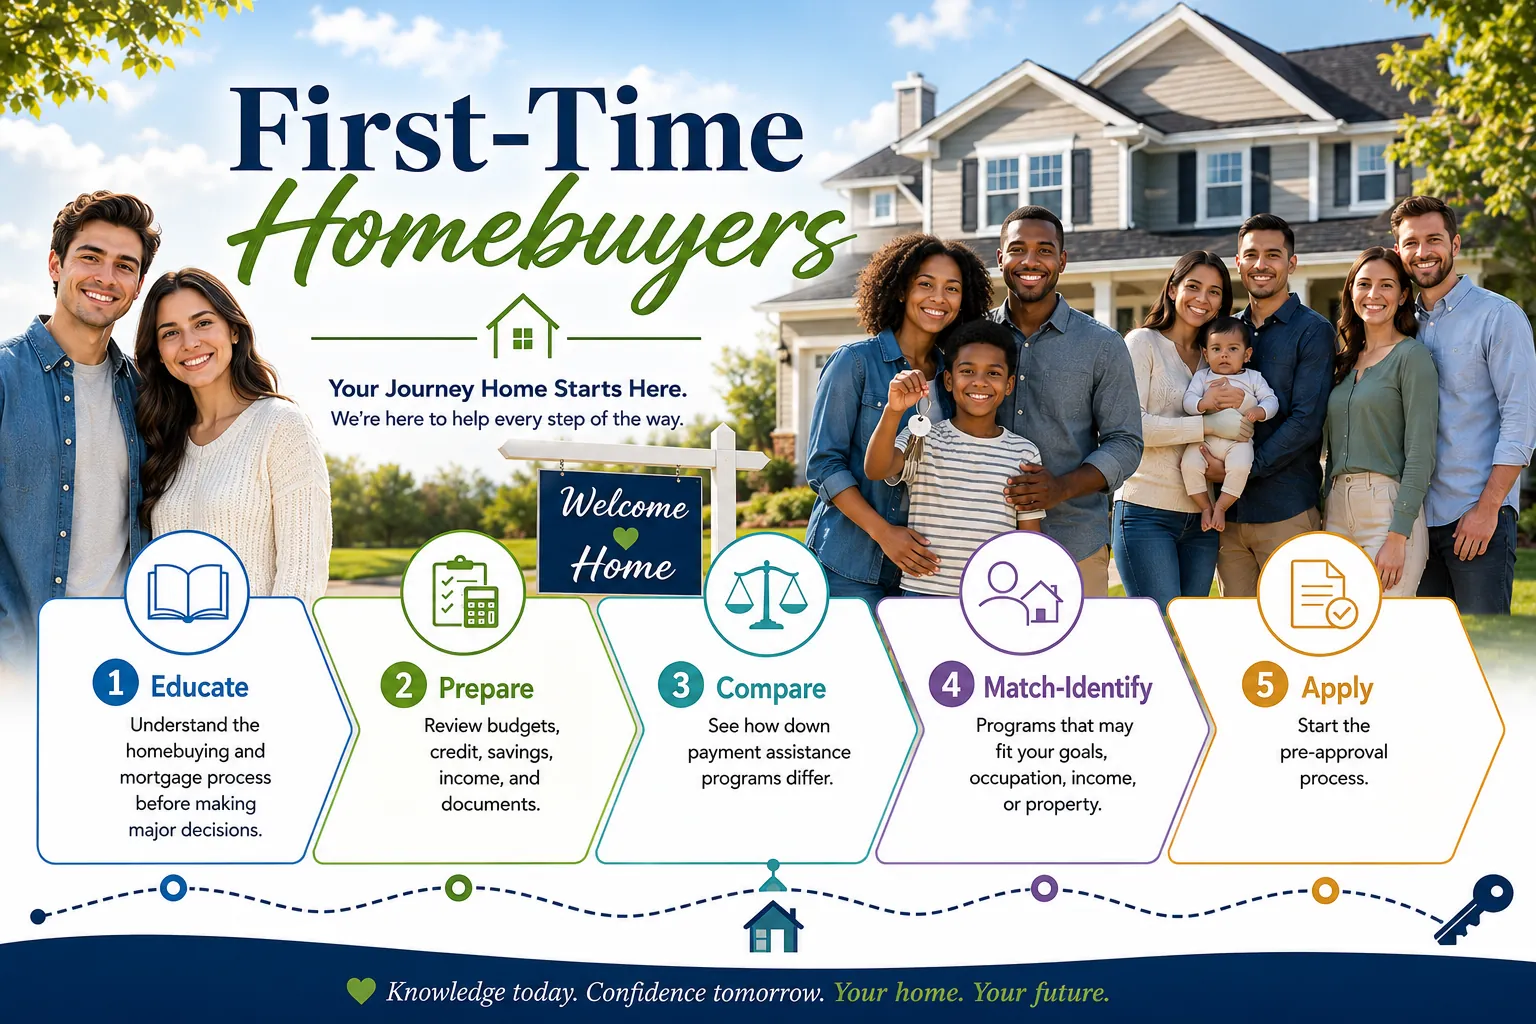
EducatePrepareCompareMatchSpeak with a Loan Officer
Buying your first home in Florida becomes easier when you understand the decisions in the right order. This guide explains how to plan your savings, compare financing, shop for a home, and move from an accepted offer to closing.
You can learn at your own pace, then discuss your circumstances with a licensed loan officer. Being a first-time buyer does not automatically qualify you for a particular loan or assistance program.
Definitions depend on the program. Some assistance programs include buyers who have not owned a principal residence in the past three years, so even past homeowners may qualify again. Check each program’s exact eligibility rules.
These steps are a practical roadmap. Some happen at the same time: for example, get financing guidance before making an offer, even if you are already browsing homes.
Build a savings plan that includes your down payment, lender and third-party closing costs, prepaid taxes and insurance, moving expenses, and an emergency reserve. A 20% down payment is not required for many eligible borrowers.
Conventional programs may allow 3% down for eligible borrowers; FHA commonly permits 3.5% for qualifying borrowers; VA and USDA may offer no-down-payment financing for eligible applicants and properties. Zero down does not mean zero cash needed at closing.
Ask about Florida Housing and local SHIP assistance, employer benefits, and eligible gift funds. Assistance may be a repayable second mortgage, deferred loan, or forgivable award; funding and conditions vary.
Helpful resources
Learn the differences between fixed-rate and adjustable-rate loans, interest rate and APR, mortgage insurance, points, and loan term. Compare total cost, not only the advertised monthly payment.
Review conventional, FHA, VA, USDA, and assistance programs. Eligibility depends on borrower, property, location, income, credit, occupancy, and current guidelines. Some Florida programs are made for people in certain jobs, like teachers, nurses, first responders, or doctors.
Florida-specific research includes property taxes, homeowners and flood insurance, HOA or condominium fees, special assessments, and whether a condo project is eligible for your chosen loan.
Helpful resources
Start with a realistic monthly housing budget: principal, interest, property taxes, homeowners insurance, mortgage insurance if required, HOA dues, and possible flood insurance. Leave room for repairs and other goals.
A lender evaluates income, existing debts, credit, assets, and debt-to-income ratio (DTI). DTI is generally monthly qualifying debt payments divided by gross monthly qualifying income; program limits vary.
Example: $2,000 of monthly qualifying debt divided by $6,000 gross monthly income equals a 33.3% DTI. This illustration is not an approval or recommended budget.
Helpful resources
Separate must-haves from preferences: commute, schools, bedrooms, accessibility, maintenance, and neighborhood. Research comparable sales and local carrying costs before touring.
During visits, look for roof age, water intrusion, HVAC condition, windows, drainage, and signs of deferred maintenance. For condominiums, review association budgets, reserves, insurance, rules, and any pending assessments.
A licensed real estate agent can help coordinate showings and explain local contract practices. Do not waive inspection or financing protections without understanding the risk.
Prequalification is an early estimate based on information provided; preapproval generally involves more detailed verification and a lender review. Neither is a final loan commitment.
Prepare photo identification, income and employment records, bank and asset statements, and explanations for unusual deposits when requested. Self-employed borrowers may need additional business documentation.
Discuss the credit inquiry process with the loan officer; whether a credit report is pulled and how it affects credit depends on the stage and process used. Keep financial circumstances stable while shopping: try not to open new credit cards, make big purchases, or change jobs.
Helpful resources
Work with your agent on price, earnest money, financing and inspection contingencies, appraisal provisions, seller concessions, and closing date. Contract deadlines matter.
Earnest money is generally credited toward the purchase if the transaction closes, but it can be at risk under contract terms if deadlines or obligations are missed.
Have your lender review the proposed payment and cash-to-close before you sign. Seller-paid costs are subject to program limits and negotiation.
Helpful resources
After a property is under contract, complete the formal application and provide requested documents promptly. Review the Loan Estimate to compare projected interest rate, APR, monthly payment, closing costs, and cash needed.
The lender orders applicable verifications, appraisal, and underwriting review. An appraisal assesses value for lending; it is not a substitute for a home inspection.
Avoid opening new debts, moving large funds without documentation, or changing employment without discussing it with your loan officer. Conditional approval may require follow-up documentation.
Helpful resources
Arrange a professional home inspection within contract deadlines. Additional inspections may be appropriate for roof, termites, wind mitigation, or other property concerns.
A title company or closing attorney coordinates title examination, lien resolution, settlement documentation, and recording. Confirm ownership and title insurance arrangements.
Obtain homeowners insurance and, where required, flood insurance. Verify wire instructions by calling the closing company using an independently confirmed number; never trust changed instructions received only by email.
Helpful resources
For most covered mortgages, you must receive the Closing Disclosure at least three business days before consummation. Compare it with the Loan Estimate and promptly ask about changes.
Confirm final funds to close, identification, signing location, and when funds and keys will be released. Florida documentary stamp and intangible taxes may be part of the transaction, depending on the loan and allocation of costs.
Closing involves signing final documents and completing funding and recording requirements. The timing of possession depends on the purchase contract and settlement arrangements.
Helpful resources
Transfer utilities, update your address, secure keys and access codes, and keep your closing documents in a safe place.
Budget for maintenance and monitor your escrow account, insurance renewals, property tax notices, and HOA communications.
Florida homeowners may wish to review homestead exemption eligibility and application deadlines with their county property appraiser.
Helpful resources
This is a general educational snapshot, not an eligibility determination or quote.
Also compare the loan term, interest rate, APR, cash to close, and estimated total monthly payment. See every option in our loan program comparison or zero down mortgage guide.
1st Florida Lending can help you review the financing paths that may fit your goals. There is no pressure and no cost to talk with us.
Educational information only. Not a loan application, preapproval, rate quote, or commitment to lend. Loan program availability, eligibility, interest rates, and down-payment-assistance funding are subject to change without notice. All financing is subject to underwriting, credit approval, income verification, property eligibility, and applicable program requirements. 1st Florida Lending is an Equal Housing Lender.