
Option 1
P&L-only
A P&L statement without the supporting bank statements. This option lists a minimum credit mid-score of 720.
Min. credit mid-score720
Max. LTV listed80%
Florida’s Top-Rated Direct Mortgage Lender4.8 Google RatingA+ BBB Rating
Qualify for a mortgage with a profit and loss statement prepared by a CPA, EA, or licensed tax preparer, instead of tax returns. 1st Florida Lending offers two P&L loan options for business owners, freelancers, and independent contractors:
A P&L loan is a mortgage option for self-employed borrowers who use business profit and loss statements to document income. The P&L statement is prepared by a licensed third party, such as a certified public accountant (CPA), an enrolled agent (EA), or a licensed tax preparer.
This option may suit established business owners, freelancers, and independent contractors who already work with an accountant and want an alternative way to document income for mortgage qualification.
You can choose between two documentation options:
A P&L statement without the supporting bank statements. This option lists a minimum credit mid-score of 720.
A P&L statement supported by two months of bank statements. This option lists a minimum credit mid-score of 640.
Both options list a maximum loan-to-value (LTV) ratio of 80%. However, the general program highlights require a minimum FICO score of 680 for 80% LTV, and a score of 640 is listed for loans up to 75% LTV. The minimum score and the maximum LTV are not an automatic combination, so the requirements for your documentation option should be confirmed together.
For loans up to 75% LTV
With a minimum FICO score of 680
Program minimum
Purchase, cash-out refinance, rate-and-term refinance, and delayed financing
Primary residences, second homes, and investment properties
The P&L-only option separately requires a minimum credit mid-score of 720.
The table below shows the limits listed for each option. Conditions and unresolved limits are shown in the table rather than simplified.
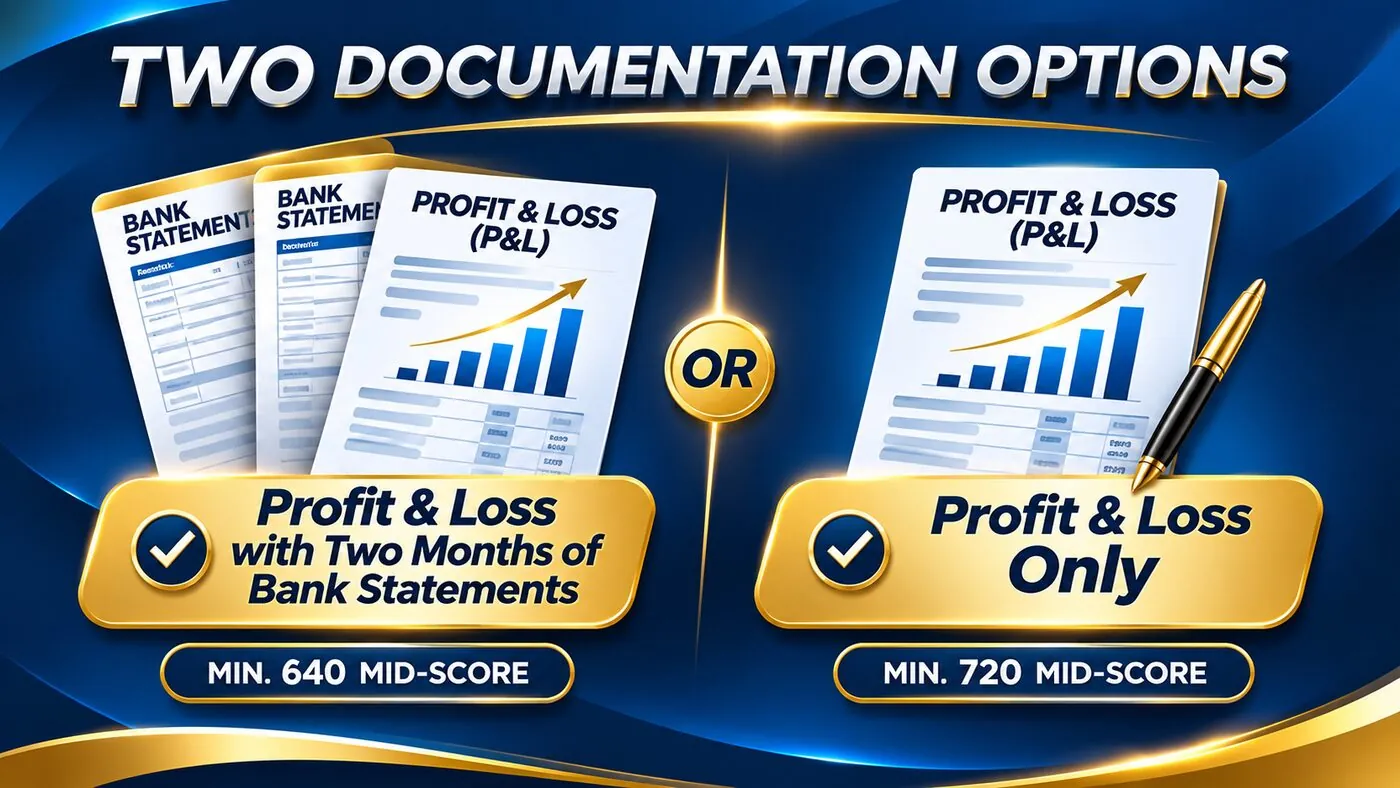
| Feature | P&L with two months of bank statements | P&L-only |
|---|---|---|
| Income documentation | P&L statement supported by two months of bank statements | P&L statement only |
| Minimum credit mid-score | 640 | 720 |
| Maximum LTV | 80% | 80% |
| Credit and LTV conditions | Program highlights list 640 for up to 75% LTV and a minimum FICO score of 680 for up to 80% LTV. | 720 minimum mid-score for this option. |
| Minimum loan amount | $150,000 (program minimum) | $150,000 |
| Maximum loan amount | $5 million | Up to $3 million |
| Business bank statements | Two months, as part of this option | Not part of this option, but at least two months are required if your tax preparer did not file your most recent business tax return |

Contact 1st Florida Lending to review your documentation option, requested loan amount, property type, and the credit and LTV requirements that apply to you. Use this checklist to organize the details before you proceed:
Both are non-qualified mortgage (non-QM) options for self-employed borrowers. The main difference is how you document your income.
A bank statement loan uses 12 to 24 months of bank statements to verify income. A P&L loan uses at least one P&L statement from your business.
P&L loan rates may be higher than conventional mortgage rates because the lender relies on alternative income documentation. Your rate depends on several factors, including:
Rates are not quoted in this overview. Contact 1st Florida Lending to request current program details for your scenario.
Yes. Eligible properties include primary residences, second homes, and investment properties, including properties purchased to start or expand a real estate portfolio.
1st Florida Lending offers alternative mortgage options, including P&L loans, bank statement loans, debt service coverage ratio (DSCR) loans, and other non-QM programs. Our team works with self-employed borrowers to help them find financing that fits their needs.
Our P&L program offers two documentation options, several loan purposes, and guidance from our loan officers throughout the process. Whether you are financing a primary home or an investment property, contact us to discuss your options and request current rates and program details. Speak with a Loan Officer today to learn more about our P&L mortgage loan program or take the first step and get started online.
There is no fixed minimum income requirement. Your P&L statement must show enough income to support your debt-to-income (DTI) ratio and the loan payment you are requesting, including property taxes, insurance, and any homeowners association (HOA) fees.
To use a profit and loss statement to document your income, the statement must:
The tax preparer must also confirm that they:
Additional bank statement requirement: If the tax preparer did not file your most recent business tax return, you must also provide at least two months of business bank statements covering the most recent two-month period.
P&L loans are designed for self-employed individuals, business owners, freelancers, and independent contractors. To qualify, you must demonstrate at least two years of consistent self-employment income, strong credit, and financial stability. Borrowers with W-2 income typically use standard income documentation instead.
The two-year self-employment history requirement is separate from the period your P&L statement covers.
Many types of self-employed businesses can qualify, including consultants, contractors, real estate agents, attorneys, doctors, dentists, accountants, freelancers, and small business owners. The key is consistent, verifiable business income, not a particular industry.
No. The minimum credit score does not automatically qualify you for the maximum LTV. The program highlights a FICO score of 640 for up to 75% LTV and a minimum score of 680 for up to 80% LTV. The P&L-only option separately requires a minimum credit mid-score of 720. Review these requirements together and confirm which combination applies to your documentation option.
Not necessarily. Your statement may be prepared by a licensed CPA, an EA, or a CTEC-registered tax preparer who is not related to you or associated with your business. It must be signed by both you and the preparer, dated within 90 days of closing, and on the preparer's official letterhead. See “What documentation is required for a P&L loan?” above for the full requirements.
Contact 1st Florida Lending to discuss your options and request current rates and program details.
This overview is for general information only and is not a commitment to lend. All loans are subject to credit approval, underwriting, and confirmation of current program requirements, which may change.
1st Florida Lending Corp · Direct Mortgage Lenders · NMLS #359304 · State #MLD1069 · 2151 Consulate Dr., Suite 8, Orlando, FL 32837 · 800-655-1345 · When Banks Say No! We Say YES!® · Equal Housing Opportunity.