1st Florida Lending — When Banks Say No! We Say Yes!

Florida’s Top-Rated Direct Mortgage Lender4.8 Google RatingA+ BBB Rating

Construction-to-Perm Loan Programs — one-time close financing from 1st Florida Lending

1st Florida Lending | Mortgage Loan Programs

Construction-to-Perm Loan Programs

Build Your Home. One-Time Close Financing. From Foundation to Keys.

DON’T JUST BUY A HOUSE, BUILD A HOME THAT REFLECTS YOUR VISION. FROM AN EMPTY LOT TO YOUR IDEAL FLOOR PLAN, EXPLORE FINANCING TO HELP BRING YOUR PLANS TO LIFE. YOUR BLUEPRINT. YOUR LAND. OUR FINANCING.

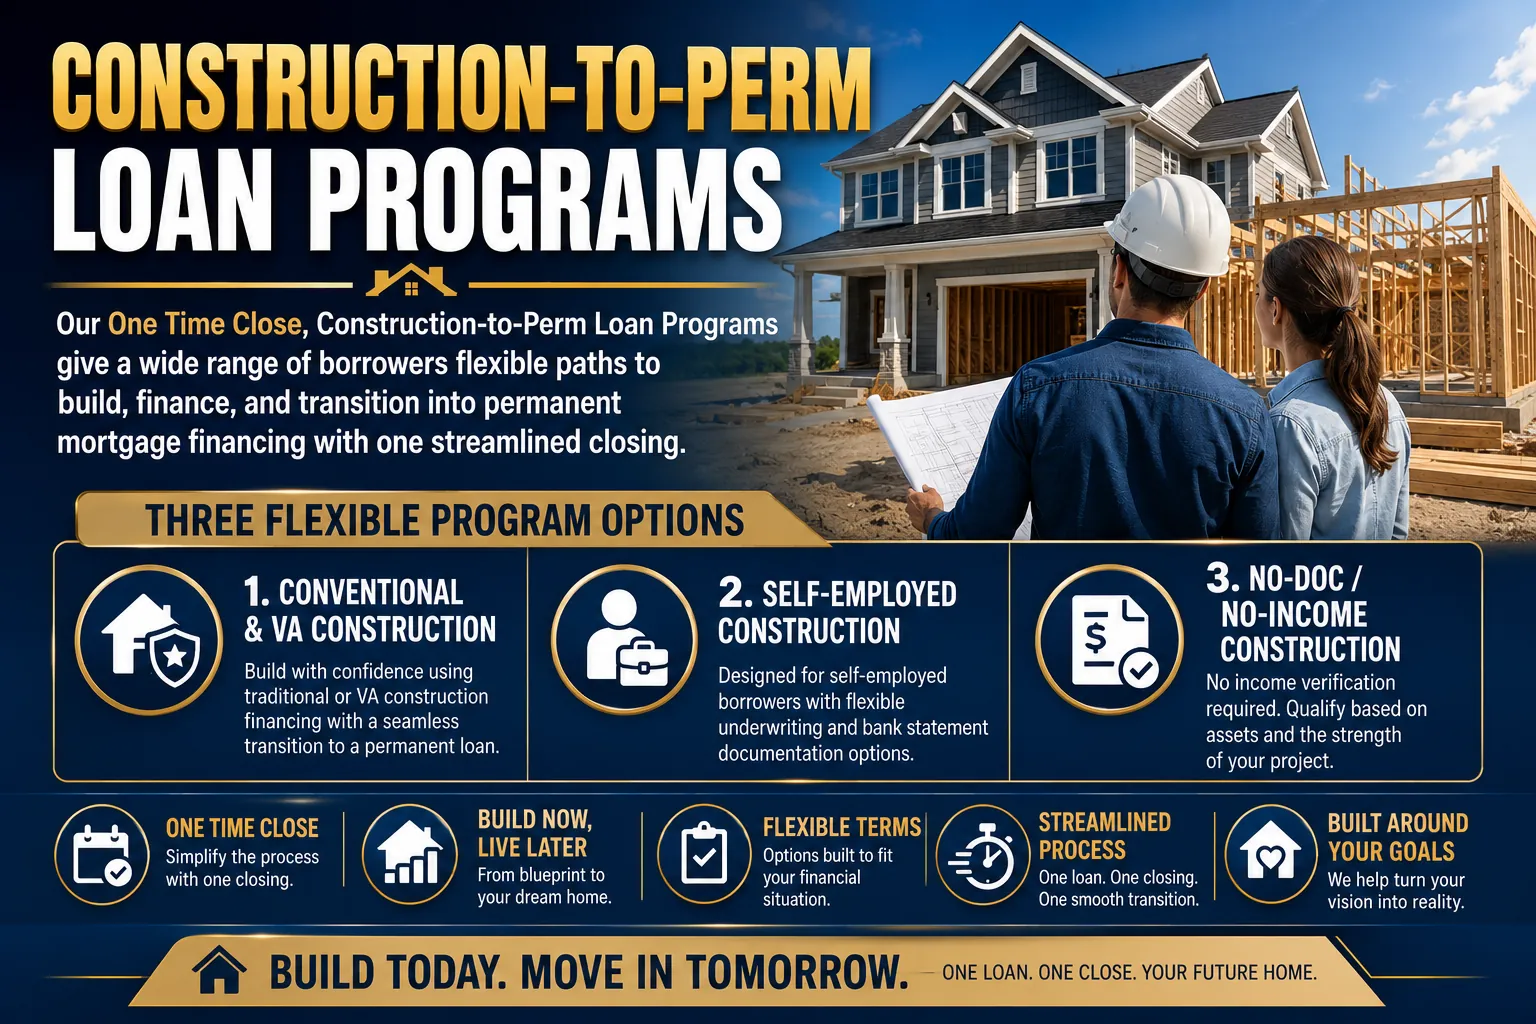
Building a home starts with a vision and a financing approach that supports it. Our One-Time Close, Construction-to-Perm loan programs offer a wide range of borrowers flexible options to finance construction and transition into a permanent mortgage through one streamlined closing. Rather than treating construction and long-term financing as separate goals, these programs bring them together in one coordinated path. Build Your Home. Finance It Once. Close One Time.

What Is Construction-to-Perm Financing?

One qualification. One closing. One loan — from foundation to keys.

A construction-to-perm (C2P) loan — often called a one-time close or single-close construction loan — combines your construction financing and your permanent mortgage into a single loan with a single closing. You qualify once, sign once, and pay one set of closing costs.

During the build, funds are released to your builder in scheduled draws as construction milestones are completed and inspected. In most programs you make interest-only payments on the amount drawn, keeping carrying costs lower while your home is under construction. When construction is complete, the loan automatically converts to your permanent mortgage — no second application, no requalification, and no second closing.

Know What You're Looking For?

Quick Search

Skip the scroll — jump straight to the construction program you want to review.

01.

Conventional & VA Construction

The traditional path for W-2 employees and salaried buyers who qualify with tax returns and pay stubs — including a VA construction-to-perm option with $0 down for eligible veterans. Build with confidence using traditional or VA construction financing with a seamless transition to a permanent loan.

  • W-2 income with traditional tax returns and pay stubs
  • One-time close construction-to-perm financing
  • Lock your permanent rate up front
  • Conventional: as little as 5% down
  • VA: $0 down with full entitlement — and no PMI
  • Underwritten on income, credit & assets

Occupancy: Primary & Second Homes

02.

Self-Employed Construction

Non-QM construction-to-perm financing for business owners, 1099 contractors, and self-employed borrowers who qualify using 12 or 24 months of bank statements instead of tax returns. Designed for self-employed borrowers with flexible underwriting and bank statement documentation options.

  • Qualify with 12 or 24 months of bank statements
  • No tax returns or W-2s required
  • One-time close construction-to-perm financing
  • Business or personal deposits accepted
  • Competitive Non-QM pricing on strong files
  • Underwritten on deposit history, credit & assets

Occupancy: Primary & Second Homes

03.

No-Doc / No-Income Construction

Investor construction financing with no tax returns, no employment verification, and no personal income documentation — underwritten on the project, the borrower's credit, and the as-completed value of the finished home. Qualify based on assets and the strength of your project.

  • No tax returns
  • No employment verification
  • No personal income documentation
  • One-time close construction-to-perm financing
  • Underwritten on credit and as-completed value
  • Spec builds and rental holds supported

Occupancy: Investment Property Only

Program Comparison at a Glance

Compare the three construction-to-perm programs

FeatureConventional & VASelf-Employed (Bank Statement)No-Doc / No-Income
Best ForW-2 employees, salaried buyers, eligible veteransBusiness owners, 1099 contractors, entrepreneursReal estate investors & builders
Income DocumentationTax returns, W-2s, pay stubs12–24 months of bank statementsNone required
Tax Returns RequiredYesNoNo
Down PaymentConventional from 5% · VA $0 down*Varies by credit & file strengthVaries by project & as-completed value
Underwriting BasisIncome, credit & assetsDeposit history, credit & assetsCredit, project & as-completed value
One-Time CloseYesYesYes
Rate Lock Up FrontAvailableAvailableAvailable
Eligible OccupancyPrimary & Second HomesPrimary & Second HomesInvestment Property Only
Loan CategoryAgency / VANon-QMNon-QM / Investor

*VA $0 down requires sufficient VA entitlement and program eligibility. All figures subject to underwriting approval. Be Advised: This program is not available for Manufactured homes

Who These Programs Are Designed For

Built for W-2 buyers, veterans, self-employed borrowers, and investors

W-2 Buyers & Veterans

Salaried and hourly employees with steady income, eligible veterans and active-duty service members, and buyers building a primary or second home who want to lock a permanent rate before breaking ground.

Self-Employed Borrowers

Business owners whose tax returns understate real cash flow, 1099 contractors and freelancers, and entrepreneurs with strong business or personal deposits — including borrowers previously declined for lack of W-2 income.

Investors & Builders

Investors building spec homes to sell, buy-and-hold investors building rentals, and borrowers who prefer not to document personal income.

How It Works

The Construction-to-Perm Process, Step by Step

  1. 1.

    Get Pre-Qualified

    We review your goals, credit, and documentation path — full doc, bank statement, or no-doc — and match you with the right program.

  2. 2.

    Finalize Plans & Builder

    Submit your building plans, budget, and builder information for review as part of the approval.

  3. 3.

    Appraisal & Approval

    The appraisal is based on the as-completed value of your home. One approval covers both the construction phase and the permanent loan.

  4. 4.

    One Closing

    You sign once. Your permanent rate structure is set, closing costs are paid one time, and construction funds are ready to deploy.

  5. 5.

    Build & Draw

    Funds are released to your builder in scheduled draws as milestones are inspected. You typically make interest-only payments on the amount drawn.

  6. 6.

    Convert to Permanent

    At completion, the loan automatically converts to your permanent mortgage — no second closing, no requalification.

Ready to build with one closing?

Tell us your lot, plans, builder, and how you want to document income — we'll match the right construction-to-perm program and quote your rate, payment, and reserves inside 24 hours.

Construction-to-Perm: Frequently Asked Questions

Answers to the most common questions about one-time close construction financing.

Direct Mortgage Lender · Licensed in Florida & California · A+ BBB RatingBuild Today. Move In Tomorrow.

  • One-Time Close
    One loan, one closing, one set of costs
  • Interest-Only Draws
    Pay only on funds drawn during the build
  • Rate Lock Up Front
    Protect your permanent rate before breaking ground
  • Primary, Second & Investment
    Owner-occupied and investor builds supported

Disclaimer

All loan programs, rates, terms, eligibility requirements, down payment requirements, and documentation requirements are subject to underwriting approval and may change without notice. Not all applicants will qualify. This page is for informational purposes only and does not constitute a loan approval, commitment to lend, or an offer to extend credit. VA loans available to eligible veterans, service members, and surviving spouses; $0 down requires sufficient entitlement. Non-QM programs have specific eligibility criteria. Property must be located in a state where we are licensed to lend. “When Banks Say No! We Say YES!®” is a registered trademark of 1st Florida Lending Corp. Equal Housing Lender. © 2026 1st Florida Lending Corp. All rights reserved. 
Be Advised: The construction-to-perm loan program is not available for Manufactured homes